Every UK limited company that receives a notice to deliver a Company Tax Return must file a CT600, with its accounts and tax computation, online to HMRC within 12 months of the end of its accounting period, and pay any corporation tax due, usually within nine months and one day. That applies even when the company made a loss or owes nothing. Get the order right (register, keep records, prepare accounts, compute taxable profit, file, pay) and the process becomes routine rather than stressful.
This guide sets out who needs to file, the key deadlines, current rates, how the return is built, the penalties for getting it wrong and the mistakes that most often trigger HMRC questions. It is written for directors of small and medium-sized companies, and figures reflect the position for the 2026 financial year; always check GOV.UK for any later changes.
Who has to file a corporation tax return
Corporation tax applies to UK resident limited companies, foreign companies with a UK branch or office, and some clubs, co-operatives and unincorporated associations. A new company must register for corporation tax within three months of starting to trade (buying, selling, employing someone or advertising all count). Once HMRC issues a notice to deliver, the company must file a return for each accounting period, whether it made a profit, a loss or neither.
Dormant companies may be able to tell HMRC they are dormant and avoid filing, but if a notice to deliver arrives, it must still be answered. Property investment companies, including those holding buy-to-let portfolios, are in scope in the same way as trading companies.
Key deadlines at a glance
| What | When |
|---|---|
| Register for corporation tax | Within 3 months of starting to trade |
| Pay corporation tax (most companies) | 9 months and 1 day after the end of the accounting period |
| File accounts with Companies House (private company) | Usually 9 months after the financial year end |
| File the CT600 with HMRC | 12 months after the end of the accounting period |
| Amend a filed return | Generally within 12 months of the filing deadline |
Note that payment falls due before the filing deadline. Plenty of directors assume they have 12 months to pay and end up with interest charges. Large companies (broadly, taxable profits above £1.5 million, shared between associated companies) pay by quarterly instalments instead, starting during the accounting period itself.
Current corporation tax rates
Since April 2023 the structure has been:
- Small profits rate of 19% for taxable profits up to £50,000
- Main rate of 25% for taxable profits above £250,000
- Marginal relief between £50,000 and £250,000, which produces an effective rate that rises gradually from 19% to 25%
The thresholds are divided by the number of associated companies (broadly, companies under common control) and reduced proportionally for accounting periods shorter than 12 months. Directors who own several companies are sometimes surprised to find each one paying more than expected for this reason.
How the return is put together, step by step
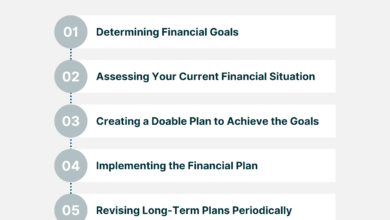
- Close the books. Reconcile bank accounts, record all sales and purchase invoices, accruals and prepayments, and agree the director’s loan account.
- Prepare statutory accounts. These follow the relevant accounting standard (often FRS 102 or FRS 105 for micro-entities) and show the accounting profit.
- Adjust for tax. Start from accounting profit, add back items that are not deductible (such as depreciation and client entertaining) and deduct capital allowances instead of depreciation.
- Apply reliefs and losses. Claim capital allowances, R&D relief where eligible, and bring forward or carry back losses.
- Complete the CT600. Enter the figures and any supplementary pages, for example for loans to participators under section 455.
- File online in iXBRL. The return, accounts and computation must be submitted electronically in tagged iXBRL format.
- Pay the tax using the company’s 17-character payment reference, and keep proof of payment.
One change catches out many small company directors: HMRC closed its free joint filing service for company accounts and tax returns in March 2025. Returns now need to be filed through commercial software or an agent. Many providers offer low-cost options for simple companies, but you can no longer rely on the old government tool.
Allowances and reliefs worth knowing
- Annual Investment Allowance gives a 100% deduction for most plant and machinery up to £1 million a year.
- Full expensing gives companies a 100% first-year deduction for qualifying new main-rate plant and machinery with no upper limit.
- Research and development relief now runs mainly through a merged scheme, with extra support for R&D-intensive loss-making SMEs.
- Trading losses can generally be carried back one year or carried forward against future profits.
- Employer pension contributions and reasonable directors’ salaries are typically deductible business costs.
Cutting running costs also improves the bottom line before tax is even considered. Our article on ways to reduce your business energy bill has some practical starting points.
Penalties for late filing and late payment
| How late the return is | Penalty |
|---|---|
| 1 day | £100 |
| 3 months | Another £100 |
| 6 months | HMRC estimates the tax and adds 10% of the unpaid tax |
| 12 months | Another 10% of any unpaid tax |
If a return is late three times in a row, the flat £100 penalties rise to £500 each. Late payment also attracts interest from the due date. Separate penalties apply for inaccurate returns, scaled by whether the error was careless, deliberate or deliberate and concealed. Companies House issues its own late filing penalties for accounts, which are entirely separate from HMRC’s.
Common mistakes that trigger HMRC queries
- Confusing the payment deadline with the filing deadline
- Claiming entertaining, fines or private expenses as deductions
- Forgetting to add back depreciation and claim capital allowances instead
- Overdrawn director’s loan accounts not repaid within nine months, which can trigger a section 455 charge
- Ignoring associated companies when applying the £50,000 and £250,000 thresholds
- Getting the accounting period wrong after changing the year end, since a tax accounting period can never exceed 12 months
Keep records for at least six years from the end of the accounting period they relate to. Good records are also your best defence if HMRC opens an enquiry.
A year-end checklist for directors
A few weeks before the accounting period ends, run through these points so there are no surprises when the numbers are finalised:
- Estimate the likely profit and tax bill, and set the cash aside in a separate account
- Decide whether planned equipment purchases should fall before or after the year end, since timing affects when allowances are claimed
- Review the director’s loan account balance and plan any repayment
- Consider employer pension contributions, which must actually be paid in the period to be deducted
- Put the payment date and filing deadline in the diary, with reminders a month ahead
DIY or use an accountant?
A simple single-director company with few transactions can file using commercial software, provided the director is comfortable with the tax adjustments. Once a company has employees, assets, property, overseas activity, associated companies or R&D, professional help usually pays for itself through fewer errors and better use of reliefs. Specialist firms can prepare the accounts and computation and file corporation tax returns on your behalf, which is particularly useful for property companies with rental income, finance costs and capital gains to deal with. Property companies buying several homes in Scotland should also look at our guide to Multiple Dwellings Relief in Scotland, and growing firms may find our piece on how to scale your business helpful for planning ahead.
This article is general information, not tax or financial advice. Speak to a qualified accountant about your company’s circumstances.
Frequently asked questions
When is corporation tax due in the UK?
For most companies, payment is due nine months and one day after the end of the accounting period. The CT600 return itself is due 12 months after the period ends. Large companies pay in quarterly instalments.
Do I need to file a return if my company made a loss?
Yes. If HMRC has sent a notice to deliver a Company Tax Return, you must file even if there is a loss or no tax to pay. Filing also records the loss so it can be used later.
What is the corporation tax rate for small companies?
Companies with taxable profits up to £50,000 pay the 19% small profits rate. Profits above £250,000 are taxed at 25%, with marginal relief in between. Thresholds are shared between associated companies.
Can I still file my company tax return free with HMRC?
No. HMRC closed its free joint filing service for company accounts and tax returns in March 2025. Returns must now be filed using commercial software or through an agent.
What happens if I file my CT600 late?
There is a £100 penalty from the first day, another £100 at three months, and tax-geared penalties of 10% of unpaid tax at six and twelve months. Interest also runs on late payments.